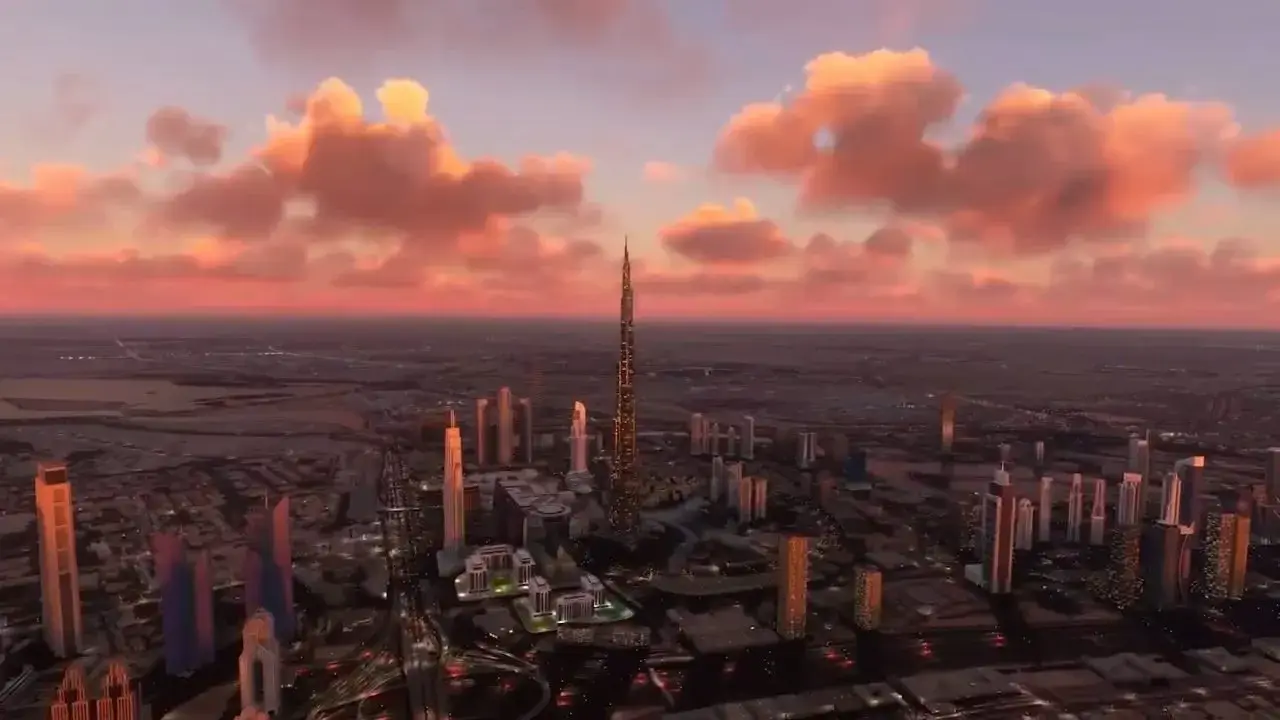
Dubai residential prices +8.4% and apartment rents +7.7% year on year; 211,092 new apartment leases over 12 months. Residential and neighbourhood retail submarkets, with Dubai Land Department data to July 2026.
Executive summary
- Prices hold despite slower sales. The 12-month median residential price in Dubai stands at AED 1,718 per sq ft, +8.4% year on year, while 13,963 sales worth AED 34.9 billion were registered in July.
- Rental demand remains firm. 211,092 new apartment leases were registered over 12 months (+5%), with median apartment rents +7.7%.
- Al Jaddaf leads the central submarkets. Residential prices are +20.4% year on year, more than double the Dubai average.
- Neighbourhood retail commands a premium. Shop rents in Liwan average AED 241 per sq ft a year, 36% above the Dubai median.
01Macro context
Activity followed the usual summer slowdown against a more cautious macro backdrop. In its July review the Central Bank of the UAE lowered its 2026 growth forecast to 1.7%, from 5.6% in the spring, while projecting a rebound of 9.8% in 2027 as the effects of the conflict fade.
Dubai prices have held up considerably better than volumes. Structural demand drivers — population growth, long-term residency, infrastructure investment and the regulatory environment — are unchanged.
02Dubai transactions
The Dubai Land Department registered 13,963 sales worth AED 34.9 billion in July 2026, compared with 20,194 in July 2025. Off-plan accounted for 69% of sales. Lower volumes alongside stable prices indicate that owners are holding rather than discounting.
Jul 2025 – Jul 2026Same month a year earlier
Source: Dubai Land Department, registered sale transactions.
03Residential market
Residential prices are measured as the median price per sq ft of registered residential sales over rolling 12-month periods, which smooths the month-to-month effect of the mix of units sold.
Source: Dubai Land Department, registered sale transactions.
| Submarket | Price AED / sq ft |
y-o-y | Apartment rent AED / sq ft a year |
y-o-y | New leases 12 months |
|---|---|---|---|---|---|
| Dubai | 1,718 | +8.4% | 74 | +7.7% | 211,092 |
| Al Jaddaf | 2,033 | +20.4% | 83 | +5.6% | 3,802 |
| Business Bay | 2,578 | +9.7% | 112 | +4.0% | 10,319 |
Source: Dubai Land Department; Key Mavens Group Research.
Al Jaddaf
A waterfront district on Dubai Creek between Downtown and the airport, served by the Creek and Al Jadaf metro stations. Residential prices are +20.4% year on year against +8.4% for Dubai; 3,802 new apartment leases were registered over 12 months (+10%).
Key Mavens Group in this submarketMontageSky Duplexes at Montage
Business Bay
Dubai’s central business district along the Dubai Canal, and one of the most active rental markets in central Dubai. Residential prices are +9.7% year on year against +8.4% for Dubai; 10,319 new apartment leases were registered over 12 months (+11%).
Key Mavens Group in this submarketTerraces Marasi Drive
04Retail market
Retail rents are measured as the median annual rent per sq ft of registered shop contracts, new and renewed, over 12 months. For neighbourhood retail, the size of the surrounding resident base and the rents achieved in comparable locations are the primary indicators of tenant demand.
Source: Dubai Land Department, registered rent contracts (new and renewed).
| Submarket | Shop rent AED / sq ft a year |
y-o-y | vs Dubai median | Apartment leases 12 months |
|---|---|---|---|---|
| Dubai | 177 | +7.8% | – | 556,639 |
| Liwan (Wadi Al Safa 2) | 241 | +7.9% | +36% | 4,835 |
| The Villa (Wadi Al Safa 5) | 150 | −4.1% | −15% | 8,041 |
Apartment leases: all registered apartment rent contracts in the community over 12 months, an indicator of the resident base. Source: Dubai Land Department; Key Mavens Group Research.
Liwan
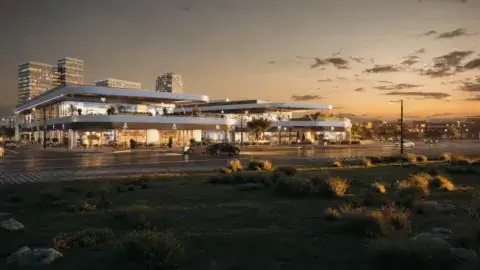
A fast-growing residential district in Wadi Al Safa 2, home to Le Meryeme – Liwan, a 113,000 sq ft community mall anchored by LuLu and scheduled to open in the second quarter of 2027. Shop rents average AED 241 per sq ft a year, above the Dubai median of AED 177, with 4,835 apartment leases registered in the community over 12 months.
Key Mavens Group in this submarketLe Meryeme – Liwan
The Villa
An established villa community in Wadi Al Safa 5, served by Le Meryeme – The Villa. Shop rents average AED 150 per sq ft a year, below the Dubai median of AED 177, with 8,041 apartment leases registered in the community over 12 months.
Key Mavens Group in this submarketLe Meryeme – The Villa
05Outlook
- The return of residents and investors in September.
- Whether rents continue to rise while sales slow, an indicator of end-user demand.
- Off-plan absorption as developers adjust launch timing.
Methodology
All transaction and rent data are Dubai Land Department (DLD) open data. Residential prices: median price per sq ft of registered residential sales over rolling 12-month periods. Rents: median annual rent per sq ft of registered rent contracts, new and renewed, over 12 months. Recent months may be revised as late registrations are recorded; rents in smaller communities rest on fewer contracts. DLD area names: Al Jadaf (Al Jaddaf), Business Bay, Wadi Al Safa 2 (Liwan), Wadi Al Safa 5 (The Villa). Macro context is attributed to the sources named in the text.
Disclaimer
This report is published for general information only. It does not constitute investment, financial, legal or tax advice, or an offer or solicitation to buy, sell or lease any property. While prepared from sources believed to be reliable, no representation or warranty is given as to its accuracy or completeness, and Key Mavens Group accepts no liability for any loss arising from its use. Past performance is not a reliable indicator of future results.
Research and media enquiries: contact Key Mavens Group.
Newsroom
More from the group
-
 Key Mavens Group ResearchIssue 06Dubai Property Market ReportOctober2026
Dubai Property Market Report: October 2026
Read →
-
 Key Mavens Group Signs LuLu Retail as Anchor Tenant at Le Meryeme Mall – Liwan
Read →
-
 Key Mavens Group ResearchIssue 05Dubai Property Market ReportSeptember2026
Dubai Property Market Report: September 2026
Read →